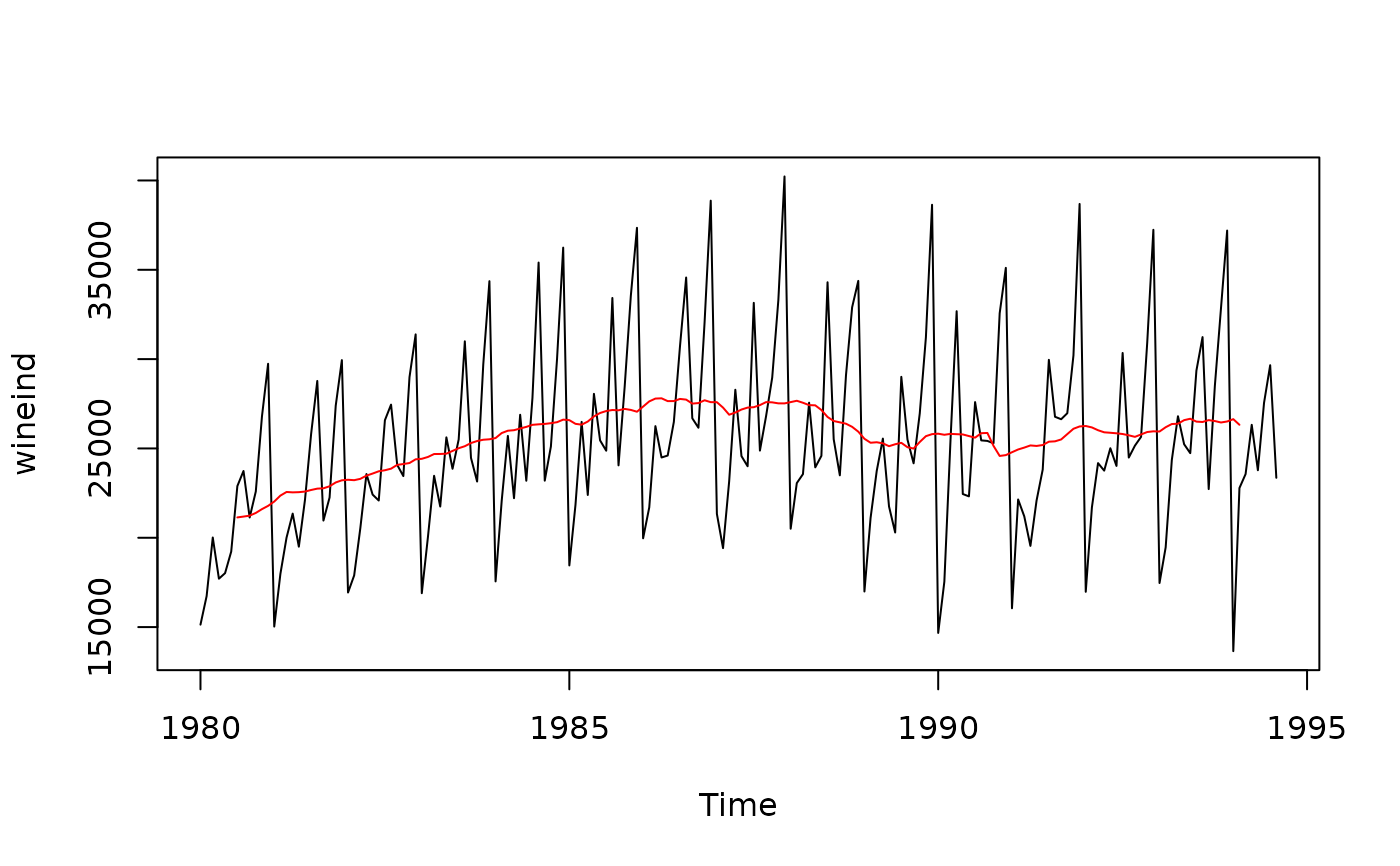
ma computes a simple moving average smoother of a given time series.
Details
The moving average smoother averages the nearest order periods of
each observation. As neighbouring observations of a time series are likely
to be similar in value, averaging eliminates some of the randomness in the
data, leaving a smooth trend-cycle component.
$$\hat{T}_{t} = \frac{1}{m} \sum_{j=-k}^k y_{t+j}$$
where \(m\) is the order and \(k=\frac{m-1}{2}\).
When an even order is specified, the observations averaged will
include one more observation from the future than the past (k is rounded
up). If centre is TRUE, the values from two moving averages (where k is
rounded up and down respectively) are averaged, centering the moving
average.